Max Pain Theory: How It Is Calculated and Why It Is Not a Prediction
Research & Invest · Updated 8 Nov 2026 · Education, not advice
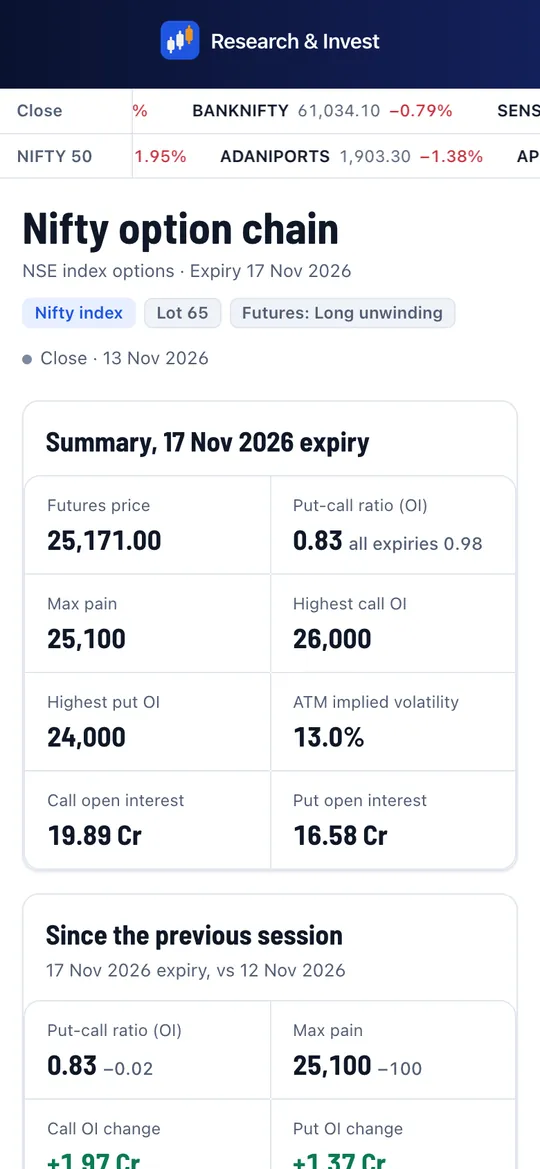
Max pain is a number you will find on almost every Indian option chain screen, usually next to the put-call ratio. It is often described as "the level where the market will expire". That description is misleading. This guide explains what max pain actually measures, shows how it is calculated with a small worked example, and explains why it should not be treated as a prediction.
What is max pain in options?
Max pain (also called the max pain point or option pain) is the strike price at which the total value of all open options at expiry would be the lowest. Put another way, if the underlying settled exactly at that strike, option buyers as a group would receive the smallest total payout, and option writers as a group would pay out the least.
The name comes from the buyer's point of view: at that level, the most option buyers see their premiums expire worthless or nearly worthless, so it causes them the "maximum pain".
Max pain is calculated separately for each underlying and each expiry. Nifty's weekly expiry and Nifty's monthly expiry will usually have different max pain levels.
How is max pain calculated?
The calculation uses only open interest and strike prices from the option chain. For each strike, you assume the underlying expires exactly there and work out what every open option would be worth.
- Take a candidate expiry price, say strike S.
- For every call with a strike below S, the call is in the money. Its value at expiry is (S − call strike) × call OI.
- For every put with a strike above S, the put is in the money. Its value at expiry is (put strike − S) × put OI.
- Calls with strikes at or above S, and puts with strikes at or below S, expire worthless and add nothing.
- Add up all the call and put values. That is the total payout if expiry is at S.
- Repeat for every strike. The strike with the smallest total is max pain.
Premiums paid are not part of the calculation. Max pain only looks at what the options would be worth at expiry.
Max pain worked example (illustrative numbers)
Here is a deliberately small option chain with five strikes, 100 points apart, around an index trading near 24,000. The OI figures are made up for illustration and are in contracts.
| Strike | Call OI | Put OI |
|---|---|---|
| 23,800 | 10 | 60 |
| 23,900 | 20 | 50 |
| 24,000 | 50 | 40 |
| 24,100 | 60 | 20 |
| 24,200 | 70 | 10 |
Now assume expiry at each strike in turn and add up the payout. Values are in points × contracts; multiply by the lot size to get rupees.
| If expiry is at | Call payout | Put payout | Total payout |
|---|---|---|---|
| 23,800 | 0 | 23,000 | 23,000 |
| 23,900 | 1,000 | 11,000 | 12,000 |
| 24,000 | 4,000 | 4,000 | 8,000 |
| 24,100 | 12,000 | 1,000 | 13,000 |
| 24,200 | 26,000 | 0 | 26,000 |
To see where one row comes from, take expiry at 24,000:
- Calls in the money: 23,800 (200 points × 10 = 2,000) and 23,900 (100 points × 20 = 2,000). Call payout = 4,000.
- Puts in the money: 24,100 (100 points × 20 = 2,000) and 24,200 (200 points × 10 = 2,000). Put payout = 4,000.
- Total = 8,000, the lowest of the five rows.
So in this example, max pain is 24,000. A real chain has many more strikes, and the calculation is the same, just longer. Our option chain pages compute it for every F&O underlying automatically.
Why do traders watch max pain?
The idea behind max pain theory goes like this. Option writers, who are often large and well-funded, hold the other side of most positions. Writers profit most when the underlying expires near max pain. Some traders believe this creates a pull towards that level near expiry, either through hedging flows or deliberate positioning.
Traders use max pain in a few ways:
- As a rough reference for where open positions are balanced.
- To see whether the current price is far above or below where writers would prefer it.
- To track how the balance of positions shifts during the week, since max pain moves as OI changes.
Is max pain a prediction of the expiry level?
No. Max pain describes where open positions currently sit. It does not forecast where the market will close, for several reasons:
- It changes constantly. Max pain is recalculated as OI changes. A level that looks firm on Monday can shift by several strikes before expiry.
- It ignores premiums. Writers who sold options at high premiums may still profit well away from max pain. The calculation does not account for what anyone paid or received.
- It does not know who holds what. OI counts contracts, not whether they are hedges, spreads or outright bets. A large put position may be one leg of a spread that profits elsewhere.
- The underlying is driven by much more than options. Index levels respond to the cash market, global cues, news, flows and results. Option positioning is one input among many.
- Index options are cash settled on the index value. Nifty or Sensex is calculated from the prices of its constituent stocks. Moving it to a specific level would need moving many large stocks at once.
In practice, expiry can and often does settle some distance from max pain. It is better treated as a description of positioning than as a target.
How max pain relates to PCR and OI
Max pain, the put-call ratio and strike-wise OI are all built from the same open interest data, so they tend to tell related stories:
- When put OI is heavy at strikes below the price and call OI is heavy above it, max pain usually lands between those clusters.
- When fresh writing moves to higher strikes on both sides, max pain tends to drift up.
- When one side unwinds sharply, for example call writers covering after a breakout, max pain can jump.
Watching how OI is changing, not just where it is, gives more context. See long buildup, short buildup and short covering for the price-and-OI framework.
Common mistakes with max pain
- Reading max pain early in the week and assuming it will hold till expiry.
- Using max pain for a thinly traded stock, where a few contracts can decide the result.
- Selling options purely because the price is "near max pain", without a plan for what happens if it moves away.
- Mixing expiries: always check you are looking at max pain for the contract you trade. The F&O expiry calendar lists the current expiries.
If you want to see how a max pain based rule would have behaved, test it on past data with real costs before relying on it. Our guide to backtesting option strategies explains what an honest test includes.
A note on risk
Options carry leverage and premiums can go to zero. A SEBI study covering FY22 to FY24 found that about 9 in 10 individual F&O traders made net losses. Max pain is a useful lens on positioning, not a reason to take a trade.
See the live option chain, PCR and max pain for every F&O stock and index, and test strategies in the strategy lab: start a free trial.