Weekly vs Monthly Expiry in India: Rules, Expiry Day and Theta
Research & Invest · Updated 8 Nov 2026 · Education, not advice
Expiry is the date on which an option or future stops trading and is settled. In India, index options come in weekly and monthly expiries, and the rules around them changed significantly after SEBI's 2024 measures on index derivatives. This guide explains how weekly and monthly expiries differ, what changed, how prices tend to behave on expiry day, and why time decay speeds up at the end.
Expiry days have been changed more than once by the exchanges, and can change again. For the exact current dates, always check the F&O expiry calendar.
What is expiry in options?
Every option and futures contract has a fixed last trading day. On that day:
- Index options (Nifty, Sensex and others) are cash settled. In-the-money options are settled in cash at the difference between the final settlement price and the strike. Out-of-the-money options expire worthless.
- Stock options and stock futures in India are physically settled. If you hold an in-the-money stock option or a stock future to expiry, you may have to take or give delivery of the shares. Brokers often ask clients to close such positions before expiry or set aside extra margin.
- Index futures are cash settled at the final settlement price.
Weekly vs monthly expiry: what is the difference?
| Weekly expiry | Monthly expiry | |
|---|---|---|
| Available on | One benchmark index per exchange (see below) | Index options, index futures, stock options and stock futures |
| Contract life | Usually a few weeks at most for the nearest contracts | Up to three months for the standard series; longer-dated index options also exist |
| Premium level | Lower, because there is less time value | Higher, because there is more time value |
| Time decay near expiry | Very fast in the final days | Slower for most of the month, fast near the end |
| Sensitivity to IV (vega) | Lower | Higher |
| Sensitivity to price swings near expiry (gamma) | Very high | Lower until the final days |
What changed after SEBI's 2024 rules on weekly expiry?
In October 2024, SEBI issued a circular with several measures to strengthen the equity index derivatives framework. The key change for expiries was:
- Each exchange may offer weekly expiry on only one benchmark index. NSE chose Nifty 50 and BSE chose Sensex. Weekly contracts on other indices such as Bank Nifty, Fin Nifty, Midcap Nifty and Bankex were discontinued from late November 2024. Monthly contracts on those indices continue.
The same set of measures also included:
- A higher minimum contract value for index derivatives, which led to new lot sizes (see F&O lot size explained).
- An additional extreme loss margin on short index options on the expiry day of that contract.
- Removal of the calendar spread margin benefit on expiry day for positions involving the expiring contract.
- Upfront collection of option premium from buyers.
- Intraday monitoring of position limits.
These measures came into effect in stages between late 2024 and 2025. Separately, the exchanges have since revised which weekday their contracts expire on. Because such details change, read the latest SEBI and exchange circulars rather than relying on any fixed weekday you may have seen quoted, and use the expiry calendar for current dates, including shifts caused by trading holidays.
Why does theta decay speed up near expiry?
An option's premium has two parts: intrinsic value (how much it is in the money) and time value (everything else). Only time value decays, and it reaches zero at expiry.
Time value does not fall at a steady rate. Under standard pricing models it shrinks roughly in line with the square root of time left, which means the last few days carry a large share of the decay, especially for at-the-money options.
Illustrative example: an ATM Nifty option might lose a few points a day with three weeks to go, but many times that per day in the final two or three sessions. On expiry day itself, remaining time value can disappear within hours.
See option Greeks explained for how theta is measured.
How do prices behave on expiry day?
Expiry days often look different from ordinary sessions. Commonly observed features include:
- Very high gamma. ATM options can double or fall to near zero within minutes as the index moves a little. Delta can flip quickly from near 0 to near 1.
- Collapsing premiums on OTM strikes. Out-of-the-money options lose value fast unless the index moves sharply towards them.
- Heavy volumes in near-ATM strikes, as traders open and close positions within the day.
- Sharp swings near the close. As positions are closed or hedged, the underlying can move suddenly in the final hour.
- Higher margins for sellers because of the additional expiry-day margin and the loss of calendar spread benefit.
These are tendencies, not rules. Some expiry days are calm; others move sharply.
How the final settlement price is set
For index options, the final settlement price is based on the closing value of the index on expiry day, calculated using the exchange's closing price method (a weighted average over the final part of the session rather than the very last trade). The exact method is set out in exchange documents. The practical point is that the last traded premium on your screen may not equal the final settlement value.
Weekly expiry: things traders often overlook
- Cheap is not the same as low-risk. A weekly OTM option costs little, but the chance of it expiring worthless is high. The total premium spent across many such trades adds up.
- Short options on expiry day carry outsized risk. Selling options to collect the final day's decay means facing peak gamma; a sharp move can cause losses much larger than the premium received.
- Charges are a larger share of small premiums. Brokerage and fees are partly fixed per order, so they bite harder on low-priced weekly options. See STT and charges on options.
- Exercise of ITM options carries STT on intrinsic value. Check how your broker handles ITM options at expiry.
- Holidays move expiry. When the scheduled expiry day is a trading holiday, expiry is usually moved to the previous trading day.
Choosing between weekly and monthly contracts
The choice depends on what the trader is trying to express. Weekly contracts react sharply to short-term moves and decay fast. Monthly contracts give a move more time to play out and are more sensitive to changes in implied volatility. Neither is better in general. Read more in implied volatility explained and option strategies for beginners.
If you want to compare how a strategy would have behaved on weekly versus monthly contracts, test it on past data that uses the actual expiry dates that were in force at the time, since these changed over the years. Our guide on backtesting option strategies explains how.
A SEBI study covering FY22 to FY24 found that about 9 in 10 individual F&O traders made net losses over that period. The speed of weekly expiries is part of what makes them risky.
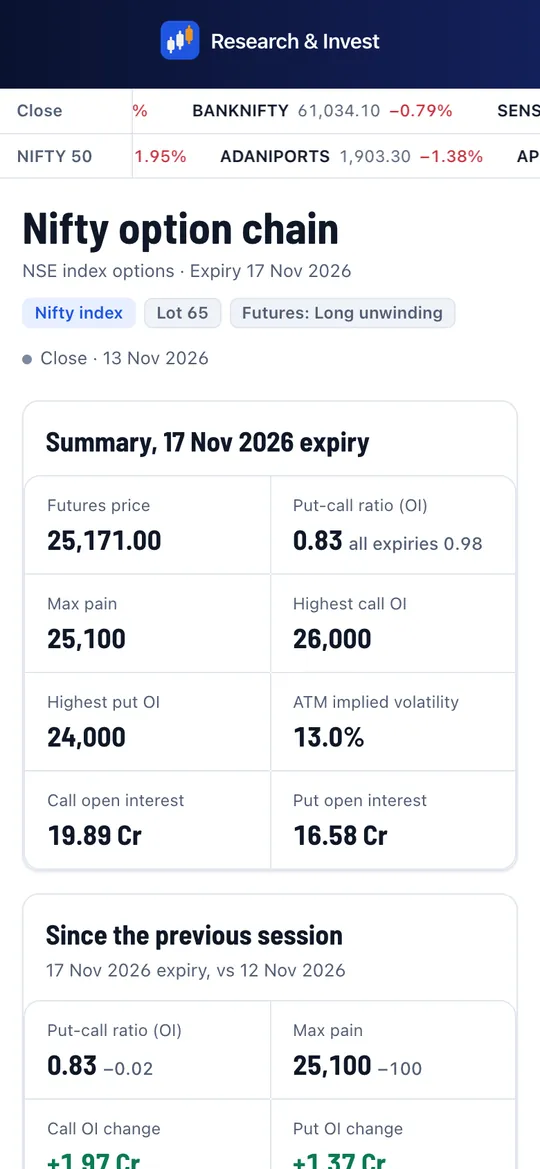
See every upcoming expiry on the expiry calendar, the live Nifty option chain with PCR and max pain, and test strategies in the strategy lab: start a free trial.